Covenants Before Capital: Diligencing the UK Lab Lease in Deep-Tech Deals
UK deep-tech spinouts tend to enter diligence with a familiar set of documents: patent filings, equipment lists, grant milestones and technical validation reports. The lease is frequently treated as an administrative artefact, filed alongside utility contracts and insurance certificates. That framing is a mistake. In a sector where runway is measured in months and cash is consumed by capital equipment, a laboratory lease is a financial instrument with contingent liabilities attached. Its covenants can call capital at precisely the moment a company can least afford it.
The liability with a laboratory attached
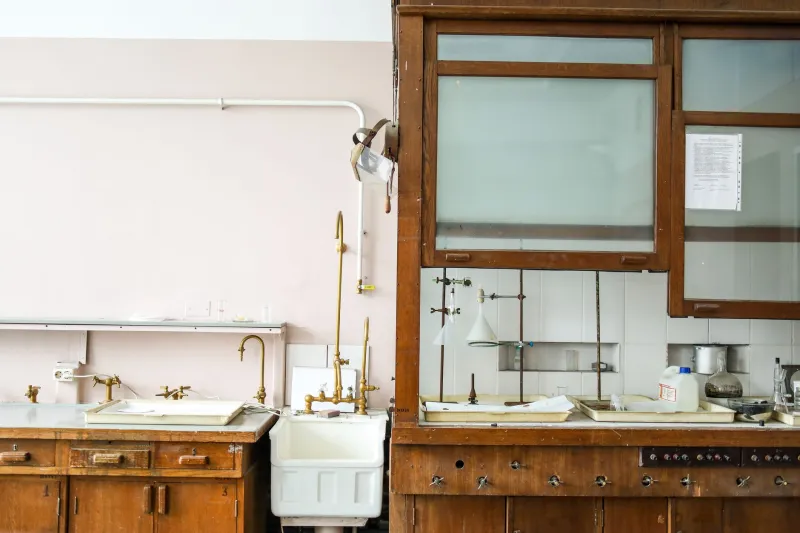
A laboratory lease is not an office lease with benches. It allocates responsibility for specialised plant, statutory compliance and reinstatement. Landlords on science parks and in urban incubators increasingly offer fitted space on a turnkey basis, but the repairing obligation often transfers a wide range of building services to the tenant: air handling units, chillers, vacuum systems, gas manifolds, water treatment and three-phase power distribution. Service charges may recover estate-wide costs that the tenant cannot control. Rent-free periods are commonly tied to completion of landlord works or tenant fit-out, so delays convert a concession into a cash burn.
Diligence teams should ask a simple question: what does the tenant actually control, and what does it merely pay for? A lease that makes the spinout responsible for maintaining plant it did not install, and cannot easily replace, is a liability with a laboratory attached. Investors should request the service charge history, the cap on recoverable costs, and the landlord's repairing covenants before modelling runway.
Dilapidations after the science
At lease end, the tenant may be required to reinstate alterations. In laboratories, alterations are rarely cosmetic. Benching, fume hoods, ductwork, gas and water systems, and electrical upgrades may all need removal. The cost can run into six figures, and it arrives after the science has been tested, not before. The Pre-Action Protocol for Dilapidations provides a process for resolving claims, but it does not cap liability. Without a schedule of condition at lease inception, the tenant bears the evidential burden of proving pre-existing condition.
This is where paper liabilities become cash calls. A spinout with eighteen months of runway may face a dilapidations provision that exceeds remaining cash. Diligence should include a surveyor's estimate of reinstatement cost, any caps on liability, and whether the landlord will waive reinstatement for specific alterations. Interim dilapidations claims are possible, so the risk is not confined to lease expiry. On science parks in Oxfordshire, Cambridgeshire and the wider Golden Triangle, and in urban incubators in Manchester and Bristol, the pattern recurs: specialist fit-out funded by the tenant, reinstatement owed to the landlord, and no reserve on the balance sheet.
Guarantees that reach the founder's balance sheet
Early-stage spinouts rarely have the trading history that landlords require. Rent deposits, parent company guarantees and personal guarantees are common responses. A personal guarantee is not a technicality. It can place a founder's home or savings at risk, often without a cap on amount or duration. Investors should identify every guarantor, the amount guaranteed, the expiry date and whether the guarantee is supported by an indemnity. An authorised guarantee agreement on assignment can also leave the original tenant liable if the assignee defaults.
Personal guarantees distort governance. A founder facing personal liability may resist necessary pivots, insolvency proceedings or a sale at a lower valuation. That is an investor risk, not merely a founder risk. Diligence should establish whether guarantees can be released, capped or replaced with a rent deposit, and whether the company has disclosed them to the board.
Break clauses and conditional flexibility
Break clauses create an illusion of flexibility. They are often conditional on no arrears, vacant possession and compliance with reinstatement obligations. In a laboratory, vacant possession may require removing fit-out and restoring services, which takes time and money. A break date missed by a day because a condition was not satisfied leaves the lease running. Diligence should map break dates against the funding plan and technical milestones. Rent reviews matter too, particularly upward-only reviews that reset the cost base regardless of market conditions.
Fit-out, grants and debt capacity
Grant-funded spinouts may use grant money for fit-out, but lease obligations can interact awkwardly with subsidy control and grant terms. If a grant requires assets to remain at specific premises, a lease break may trigger clawback. Leasehold improvements are also difficult to finance. Banks rarely lend against them, which limits debt capacity and pushes the burden onto equity. Investors should read the lease alongside the grant agreement, not in isolation.
A lease diligence checklist
For UK deep-tech deals, the lease diligence pack should include: the schedule of condition; reinstatement obligations and any caps; service charge history and caps; rent review basis; break conditions and dates; personal guarantees and authorised guarantee agreements; fit-out obligations and landlord works; allocation of statutory compliance; insurance obligations; utilities capacity; permitted use; assignment and subletting restrictions; and energy performance obligations. Each item should be modelled against the cash runway, not left in the legal folder.
Conclusion
The lab lease is not back-office. In a market where suitable space is scarce and landlords hold negotiating leverage, lease covenants can consume a funding round before the first product ships. Investors should treat the lease as a core diligence document, alongside IP and equipment. Ask for it early, model the exit costs, and negotiate caps before signature. The cheapest moment to fix a lease liability is before the first cheque clears.